There's that magical moment when your home hits the market in Myrtle Beach and you wake up to not one, not two, but three, four, or even five offers sitting in your inbox. Your heart races. You've done it. You're about to make serious money from this sale. But then reality sets in, and suddenly you're staring at those offers wondering, "Wait, which one should I actually choose?"
I've been in this position with sellers countless times, and I can tell you this: the excitement is real, but it can also cloud your judgment. The highest bid is not always the best one. That's the truth many sellers don't want to hear when they're seeing dollar signs. But trust me, choosing based solely on price is often the fastest way to end up with a deal that falls apart at the last second.
Why More Money Isn't Always the Answer
Let me paint a picture. You have two offers on your Myrtle Beach property. One is for $425,000 with a mortgage contingency, a request for you to cover $15,000 in closing costs, and a 45-day closing timeline. The other is for $410,000, all cash, zero contingencies, 15-day closing. Which would you pick?
Most sellers initially jump at that extra $15,000. But here's what they don't think about: that first offer might not even make it to closing. Mortgage contingencies mean the buyer's loan could fall through. Asking you to cover closing costs means your net proceeds are actually lower. And 45 days? That's a long time to wait and worry.
When sellers review offers, they don't just look at numbers. They evaluate certainty: who's most likely to close smoothly, on time, and without complications. This means the strongest offer isn't always the highest one – it's the one that feels safest.
In my experience working with sellers throughout Myrtle Beach, the offers that actually close smoothly are the ones that balance multiple factors. Price matters, sure, but so does everything else.
The Real Strength of an Offer
The strongest bid often balances price with financing strength, contingencies, earnest money and closing timeline rather than simply offering the highest dollar amount. When I'm comparing offers for my sellers, I always look at the complete picture.
Let me break down what actually matters:
Financing Type: Cash and conventional loans are attractive because they involve fewer hurdles than government-backed loans. A cash buyer or someone with a conventional loan pre-approval is significantly more likely to close than someone relying on an FHA or VA loan (though VA and FHA buyers can certainly close successfully with the right preparation).
Contingencies: Every contingency is a potential exit ramp for the buyer. An inspection contingency? That's normal. But a buyer who's requesting multiple contingencies or adding conditions like "seller pays for new roof" is essentially keeping one foot out the door. Sellers prefer clean, simple offers that reduce uncertainty. Keep the contract concise, include only essential contingencies, and avoid unnecessary requests like extra closing costs or home warranties.
Earnest Money Deposit: A strong offer is usually between 2% and 3% of the purchase price. This shows the buyer is serious and has skin in the game. A buyer who puts down 3% is much more committed than one who puts down 1%.
Closing Timeline: Faster is better, but only if it's realistic. A 10-day closing can seem attractive, but if the buyer can't realistically get financing approved in that timeframe, you're looking at a renegotiation or a deal that falls through.
The Creative Elements That Can Seal the Deal
Sometimes the difference between two comparable offers comes down to creativity. As a real estate agent, I've seen buyers and sellers find innovative ways to make their offers more attractive.
With multiple offers, the home seller will be most concerned about the guaranteed net dollar amount they'll get in the end. Plan with your budget so you can avoid asking the seller to pay for things like your closing costs or any type of minor up-front repairs.
Some offers include escalation clauses. This is a tool where a buyer agrees that if a competing offer comes in higher, their offer automatically increases by a set increment (say $2,000) up to a certain maximum. It keeps the buyer competitive without them having to guess the winning price. As a seller, these can be appealing because they show confidence from the buyer.
Other buyers offer to cover the seller's closing costs or offer flexible closing dates. These concessions might sound small, but they can be huge to a seller who needs to coordinate their move or wants to walk away from closing costs they weren't expecting.
How I Handle Multiple Offers in Myrtle Beach
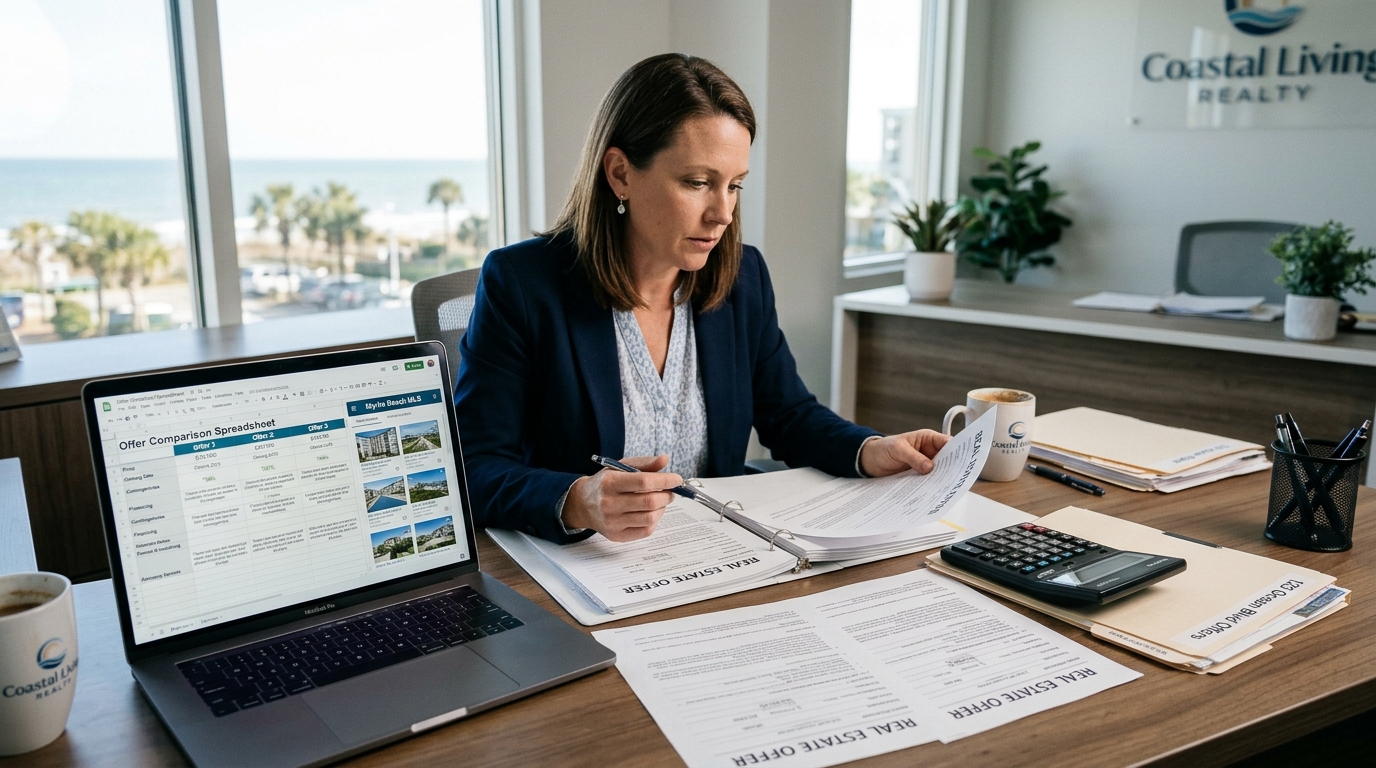
When one of my sellers gets multiple offers, we don't just line them up by price and pick the highest. Instead, I create a detailed comparison that shows all the terms side by side. I ask my sellers important questions first: What matters most to you? Do you need to close quickly? Would you prefer a cash buyer even if the price is lower? Are you concerned about contingencies?
Understanding what they hope to get out of the transaction will come into play when multiple offers are on the table. Once I know what my seller values most, I can evaluate each offer through that lens.
I also set clear deadlines when multiple offers come in. Establish a deadline for receiving offers to create urgency and allow for organized review. For sellers, setting clear offer deadlines and reviewing offers helps manage the process effectively. This gives all buyers a fair chance to submit their best offers and prevents offers from trickling in one after another for weeks.
What NOT to Do
There are a few mistakes I see sellers make when they're excited about multiple offers. First, don't assume the buyer with the highest price will actually close. I've watched deals fall apart when buyers discover their mortgage won't be approved for the final offer price or when inspections reveal issues the buyer uses as leverage to renegotiate.
Second, don't ignore your gut feeling about a buyer. Sometimes an offer just feels off. Maybe the buyer's agent seems unresponsive. Maybe there are red flags in the financing. Consider other factors like contingencies: Are there any red flags, such as multiple contingencies or lengthy inspection periods?
Third, don't let emotion override strategy. Yes, that top offer feels amazing right now, but will it feel amazing if it falls through two months later and your house is back on the market?
The Bottom Line for Myrtle Beach Sellers
Multiple offers are exciting, and they do give you leverage. But leverage is only valuable if you use it wisely. Take the time to evaluate each offer completely. Look at financing, contingencies, earnest money, closing timeline, and any creative terms the buyer included. Compare the offers side by side and calculate your actual net proceeds from each one, not just the purchase price.
If you're selling a property in Myrtle Beach and find yourself with multiple offers, that's when having an experienced local real estate agent really matters. I work with my sellers to break down each offer, answer tough questions, and make sure we're choosing the one most likely to actually close and put money in your pocket.
Visit my profile on HOUSEJET to see current Myrtle Beach listings and market data, or reach out if you're thinking about selling. Multiple offers aren't just about picking the biggest number. They're about picking the safest bet, and that's where my expertise comes in.